The Lehigh Valley’s median home sales price reached $360,000 in April 2026, a 4.3% increase over the year before, as buyers competed aggressively for a thin supply of listings and pending sales surged 18.5%.
The latest data from the Greater Lehigh Valley Realtors (GLVR) paints a picture of a market still defined by strong demand and stubbornly low inventory. Even as the number of completed sales fell, more buyers went under contract, prices ticked upward, and homes continued to sell fast and close to their asking prices. For all the pressure on affordability, the region remains a relative bargain compared with the broader Northeast.
Prices Push Higher
The median sales price across Lehigh and Northampton counties rose to $360,000 in April, up 4.3% from $345,000 a year earlier, according to GLVR’s monthly market report. Sellers continued to command strong terms: the percentage of original list price received climbed to 101.4%, meaning the typical home sold for slightly more than its asking price.
Homes also moved quickly. The median time on market was 23 days in April, two days faster than the same month in 2025. That pace reflects a market where well-priced listings draw immediate interest and leave limited room for buyers to negotiate. For sellers, the conditions are favorable; for buyers, they often mean acting fast and bidding at or above asking to secure a home.
Demand Outruns Supply
Pending sales, homes that went under contract during the month, jumped 18.5% year over year to 679 listings, a sign of robust buyer appetite. At the same time, closed sales fell 16.1% to 452, a gap that underscores how tight conditions can slow the pipeline even when interest is high. The mismatch between strong contract activity and falling completed sales points to a market where willing buyers simply cannot find enough homes to purchase.
Inventory remains the central constraint. Just 643 units were available across the two counties in April, down 6.3% from a year earlier. That left the region with only 1.2 months of supply, far below the five to six months generally considered a balanced market, and the figure was itself down 7.7% from a year earlier. New listings totaled 752, down 0.7% from a year earlier, doing little to ease the squeeze. When supply is this thin, even a modest uptick in demand can drive prices higher and shorten the time homes spend on the market.
Median sales price: $360,000, up 4.3%
Pending sales: 679, up 18.5%
Closed sales: 452, down 16.1%
Inventory: 643 units, down 6.3%, or 1.2 months of supply
A Relative Value in the Northeast
Even with prices rising, the Lehigh Valley continues to stand out as comparatively affordable. GLVR President Cliff Lewis pointed to the regional gap, noting that “the Northeast median home price topped $510,000 in April, while the Lehigh Valley median sales price came in at $360,000.”
That roughly $150,000 difference helps explain why the area keeps attracting buyers from higher-cost markets in New Jersey, New York and eastern Pennsylvania, where commuter access and lower price points make the region appealing. GLVR CEO Justin Porembo said affordability concerns and limited inventory continue to shape how buyers behave in the market.
The dynamic cuts both ways. The same relative affordability that draws in out-of-area buyers adds to local demand, intensifying competition for the handful of homes that come up for sale and putting upward pressure on prices. For longtime residents, that can mean tougher competition and rising costs even as the region keeps its reputation as one of the more attainable corners of the Northeast.
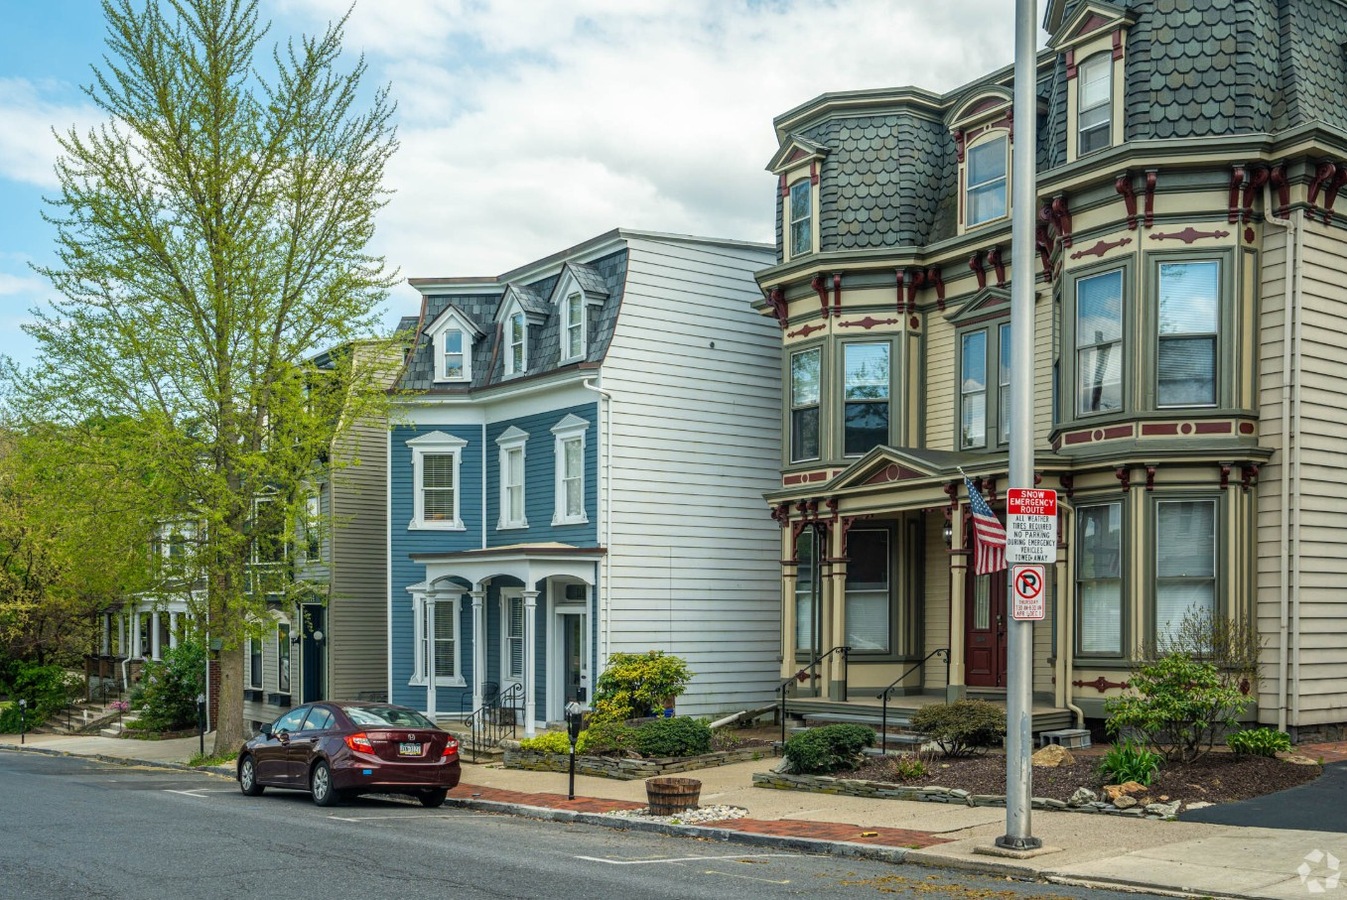
Rowhomes in Easton. The Lehigh Valley’s relative affordability continues to draw buyers from higher-cost parts of the Northeast.
Mortgage Rates and Affordability
Borrowing costs remain a key variable for buyers weighing whether to enter the market. The average 30-year fixed mortgage rate stood at 6.47% as of June 18, 2026, according to Freddie Mac, down slightly from the prior week and below the 6.81% averaged a year earlier.
While easing rates offer modest relief, the combination of higher prices and limited choices keeps affordability tight. Buyers are increasingly turning to newly built homes as an alternative. Porembo said buyers are “increasingly looking at new construction communities, particularly as builders continue adding inventory and offering move-in-ready opportunities.” Through the first four months of 2026, 87 new-construction properties sold at a median price of $560,000, with another 144 under agreement.
The Carbon County Picture
Just north of the core Lehigh Valley, Carbon County offered a steadier and more affordable alternative. The median sales price there held at $250,000 in April, unchanged from the prior year. Pending sales rose to 79 from 54, while closed sales slipped slightly to 43.
Inventory in Carbon County was looser than in the urban core, with 129 units available and 2.2 months of supply, nearly double the cushion found in Lehigh and Northampton counties. Homes there took longer to sell, averaging 55 days on market, reflecting the area’s more rural character and lower price tier.
Lehigh Valley Home Prices at a Glance
Median sales price reached $360,000 in April 2026, up 4.3% from $345,000.
Pending sales jumped 18.5% to 679 listings, signaling strong demand.
Closed sales fell 16.1% to 452 amid limited supply.
Inventory was just 643 units, or 1.2 months of supply, down 6.3% from a year earlier.
Homes sold in a median of 23 days at 101.4% of list price.
The Northeast median topped $510,000, keeping the Lehigh Valley a relative value.
The average 30-year mortgage rate was 6.47% as of June 18, 2026.